Local claim risks
- Fire spreading between attached homes
- Roof & parapet leaks
- Burst pipes
- Coastal surge (flood)
- Sewer backup
Housing mix
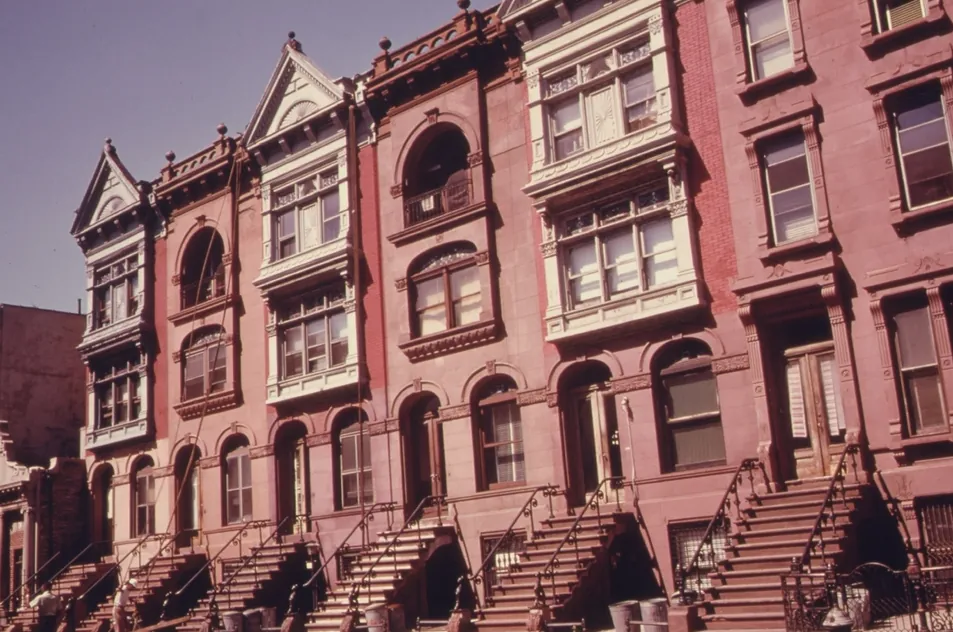
Brooklyn mixes 19th-century brownstones and brick rowhouses with frame two-families, prewar apartment buildings and a fast-growing stock of new condominiums.
Areas we visit
Park Slope, Bedford-Stuyvesant, Crown Heights, Carroll Gardens, Red Hook, Bay Ridge, Flatbush, Gerritsen Beach
Brownstones, rowhouses and party walls
Much of Brooklyn’s housing was built in long attached rows. A fire that starts in one house can send smoke, heat and firefighting water into its neighbors, and a flat roof that fails over one home can leak along a shared parapet into the next. That makes the first job of any insurance appraiser in Brooklyn a careful scope: which damage is yours, which came from next door, and what it really costs to restore a 19th-century interior with plaster cornices, pier mirrors, pocket doors and stoops of brownstone or limestone.
Sandy, Ida and the waterfront
Superstorm Sandy in 2012 flooded low-lying parts of the borough, including Red Hook, Coney Island, Sea Gate, Manhattan Beach, Gerritsen Beach and the Gowanus area. In 2021 the remnants of Ida brought intense rain that backed up sewers and flooded basements far from the shoreline. Floodwater is generally excluded from homeowners policies and handled, if at all, under NFIP or private flood coverage; sewer or drain backup is usually an optional endorsement. Untangling those sources is often where a Brooklyn claim gets stuck. Our guide to basement water, sewer backup and flood walks through the differences.
Where Brooklyn claims get disputed
- Ornamental plaster, original millwork and parquet priced as builder-grade replacements.
- Smoke damage in an adjoining home dismissed as “cosmetic.”
- Roof replacement limited to a patch when the membrane cannot be repaired in sections.
- Brownstone facade and stoop repairs left off the scope.
- Basement apartments where the water source is contested.
Two-family and three-family frame houses in neighborhoods like Bushwick, Sunset Park and Bensonhurst raise a different set of questions. Tenant-occupied units may bring loss-of-rents coverage into play, and older vinyl or aluminum siding laid over original clapboard can hide damage until the outer layer comes off. A good scope accounts for what is likely underneath, not just what is visible on the day of the inspection.
Illustrative example: if a carrier prices a damaged parlor-floor ceiling as new drywall, while a plasterer quotes three-coat work with a restored cornice, the difference on one room alone can run into thousands of dollars. Appraisal exists to settle exactly that kind of pricing gap.
Historic districts and permits
Brooklyn Heights became New York City’s first historic district in 1965, and many neighborhoods since, including much of Park Slope, Fort Greene, Clinton Hill and Bedford-Stuyvesant, have landmark protections. Facade, window and roofline work there may require Landmarks Preservation Commission approval and matching materials. Whether added costs are paid depends on your policy’s ordinance-or-law coverage, so read it closely. We serve Williamsburg, Greenpoint, Bushwick, Crown Heights, Flatbush, Ditmas Park, Sunset Park, Bay Ridge, Bensonhurst, Sheepshead Bay and Canarsie as well. If fire is the issue, see our fire and smoke damage appraisal page.
Appraisal services for Brooklyn properties
Every New York Insurance Appraiser service is available in Brooklyn and across Kings County, including:
- Appraisal Clause Representation
- Homeowners Claim Appraisal
- Co-op, Condo & Commercial Appraisal
- Roof & Hail Damage Appraisal
- Windstorm & Tornado Appraisal
- Hurricane & Nor’easter Appraisal
- Water Damage Appraisal
- Fire & Smoke Damage Appraisal
Brooklyn claim questions
A fire next door damaged my rowhouse. Whose insurance pays?
Usually you start with your own homeowners policy for damage to your home, and your carrier may pursue the neighbor later. Appraisal can help if you and your insurer disagree on the amount of that damage.
Do landmark rules raise what my insurer owes?
They can raise the cost of repair. Whether your policy pays that increase generally depends on its ordinance-or-law coverage and limits. Check your policy or ask a New York attorney.