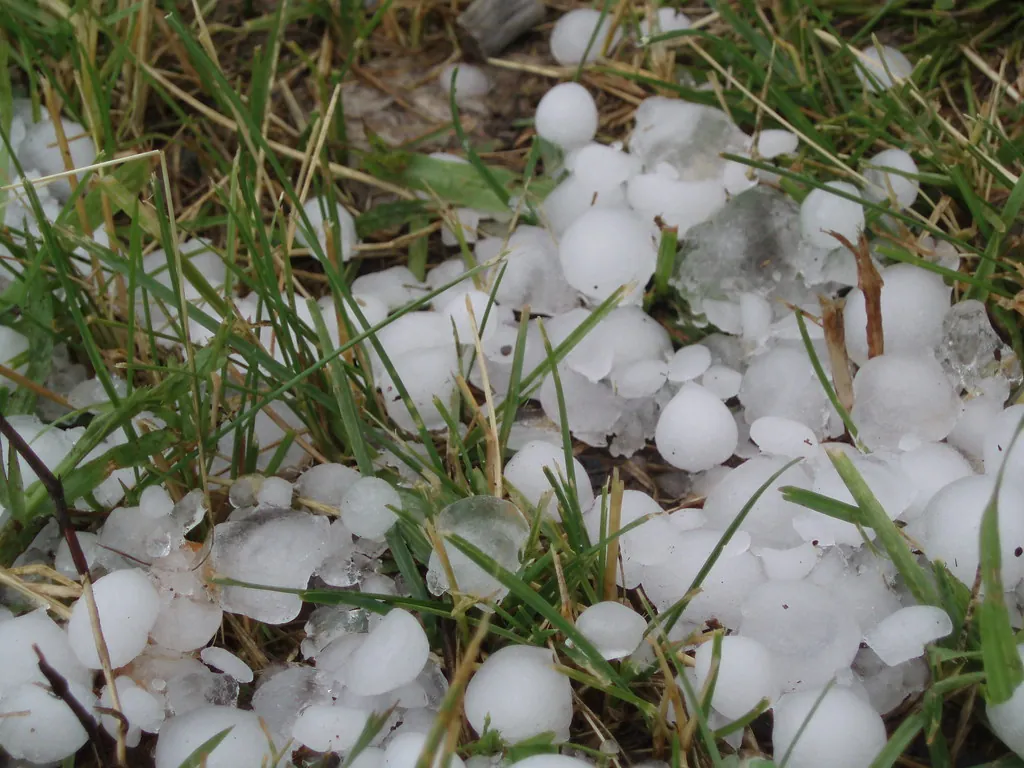
Hail in New York is real, just less famous
New York does not get Plains-sized hail every spring, but summer thunderstorms in the Hudson Valley, the Capital Region and Western New York regularly bring hail large enough to bruise asphalt shingles, dent aluminum gutters and crack vinyl siding. A careful hail damage appraisal is often the difference between a full roof and a patch that leaks next winter.
How we document a hail roof
- Test squares on each slope, marked and photographed so the other appraiser can verify the count.
- Soft metals first: vents, flashing, gutters and downspouts show the size and direction of the hail.
- Measurements and pitch, cross-checked with our roof area and pitch estimator.
- Shingle condition: age, brittleness and whether a repair is physically possible without breaking surrounding shingles.
- Collateral items: skylights, window wraps, decks and outdoor equipment.
Repair versus replacement
Most hail disputes come down to whether scattered damage can be repaired. That turns on discontinued shingle lines, how brittle an older roof has become, and whether repairs would leave a mismatched slope. Slate and cedar roofs, common on older Westchester and Hudson Valley homes, add specialized labor that generic estimates often underprice. Metal and flat roofs on commercial or agricultural buildings bring their own testing and repair questions.
Matching is another frequent sticking point. If the insurer approves replacing two slopes of a four-slope roof but the shingle colour has been discontinued, the finished roof may look visibly patched. New York does not have a single statute that answers every matching question, so the result depends heavily on policy wording and the facts. We document available products, colour samples and manufacturer notices so the panel can see whether a uniform appearance is realistically achievable without replacing more of the roof than the carrier proposed.
Deductibles and timing
Most New York homeowners policies apply the standard all-perils deductible to hail, though some carry separate wind or hail deductibles; read your declarations page. Hail damage can go unnoticed until a leak appears months later, so document the storm date and report promptly. Our roof leak claims guide explains why winter leaks are sometimes traced back to an earlier storm. Keep a note of local storm reports for the date you believe the hail fell.
When wind is part of the story
Hail often arrives with damaging gusts. If shingles are creased or missing as well as bruised, our windstorm appraisal page covers how we separate and price the two.
Questions about roof & hail damage appraisal
Can I appraise just the roof and not the rest of the claim?
Usually the appraisal covers whatever amounts remain in dispute. If only the roof is contested, the panel can focus on that portion.
Does an older roof mean I cannot win a replacement?
Not automatically. Age affects depreciation and whether repairs are feasible, but if hail damage is accepted the panel values what a proper repair requires.
How soon after a hailstorm should I act?
Report promptly and document the storm date. Many New York policies require prompt notice and limit suits to two years from the loss, so check yours.