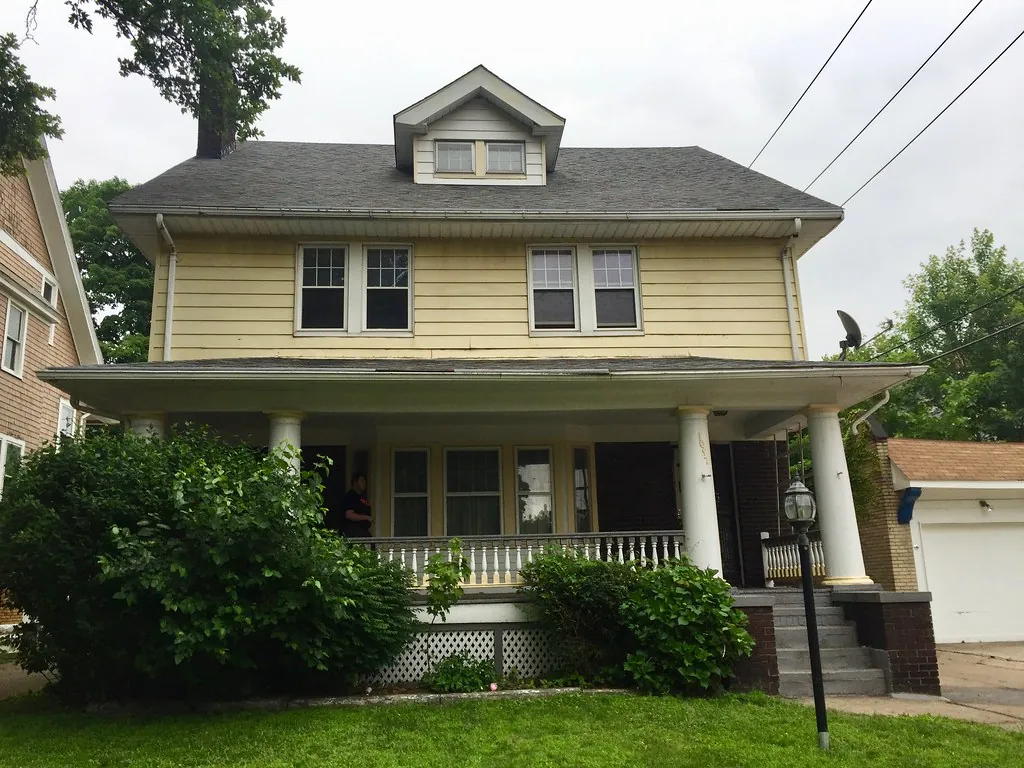
New York housing is not one-size-fits-all
A sound homeowners insurance appraisal has to start with the building in front of us. A South Shore Long Island high-ranch, a Westchester Tudor with slate details, an Albany brick rowhouse and a Rochester Victorian with original trim each carry costs that a generic estimate tends to flatten. Older plaster walls, balloon framing, party walls and narrow lot access all change how a repair is actually done.
Gaps we see in carrier estimates
- Matching. Siding, roofing or flooring that can no longer be matched, leaving a patchwork the policy may not intend.
- Code items. Upgrades the local building department requires, where your policy includes ordinance-or-law coverage.
- Access and logistics. Scaffolding on attached homes, permits for street dumpsters in New York City, hand-carrying debris through narrow passages.
- Interior detail. Crown moulding, plaster repair, built-ins and paint lines that stop at the wrong wall.
- Contents and living expenses. Personal property pricing and additional living expense that never made it into the first offer.
These omissions are rarely dramatic on their own. A missing line for detach-and-reset of a gutter, a paint allowance that covers one wall instead of the whole room, or a plaster ceiling priced as drywall can each look minor. Added together across a whole house, they often explain most of the gap between what the insurer paid and what a contractor will actually charge. We look for that pattern first, because it tells us whether the dispute is about scope, price or both, and whether appraisal is likely to change the outcome in a meaningful way.
How the work unfolds
We start with your policy declarations and the carrier’s estimate, then inspect the property and build our own line-item valuation. If the gap is real, appraisal is demanded in writing and we work with the insurer’s appraiser to narrow it. Anything left goes to an umpire. You can see each stage in our appraisal walkthrough.
Replacement cost and the holdback
Many New York homeowners policies pay actual cash value first and release the depreciation holdback once repairs are complete. An appraisal award that separates replacement cost from actual cash value makes that second payment far easier to collect. The ACV and RCV holdback calculator shows how the numbers usually fit together.
Who this service suits
Owners whose claim is accepted but underpaid, whether after a Long Island windstorm, a Syracuse ice dam or a Queens kitchen fire. If the insurer denied the claim entirely, a New York attorney is usually the better first call.
Questions about homeowners claim appraisal
Does appraisal cover contents as well as the house?
It can. If the disagreement is about the value of personal property or additional living expense, those amounts can generally be appraised alongside the dwelling.
Will appraisal slow down my repairs?
Not necessarily. Many owners make emergency repairs and keep documenting, so check your policy’s duties after loss and keep photos and receipts.
Do you work on two-family homes I live in?
Yes. Owner-occupied two- to four-family homes, common in Buffalo, Queens and the Capital Region, are often written on homeowners forms and can be appraised the same way.