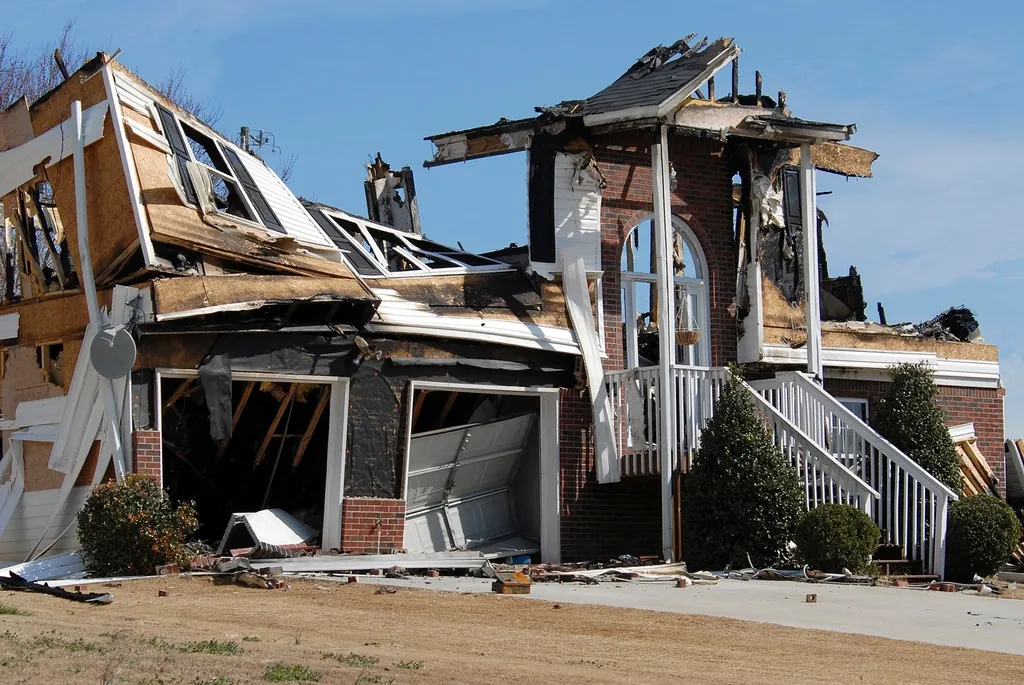
Fire in close quarters
Much of New York lives wall to wall. Brooklyn rowhouses, Queens attached brick homes, Albany brownstones and Buffalo doubles share party walls, attics and roof planes, so a fire next door can become your claim too. Superstorm Sandy’s Breezy Point fire showed how quickly flames move through dense housing. A careful fire damage appraisal accounts for heat, smoke and water from firefighting, not just the room where it started.
Where the numbers usually split
- Smoke migration. Soot travels through ductwork, wall cavities and shared stairwells. Insurers often price cleaning where replacement or sealing is needed.
- Odour. Lingering smoke odour in plaster, insulation and framing can require more than surface treatment.
- Water from suppression. Hoses and sprinklers soak floors below the fire.
- Code upgrades. Older buildings rebuilt after a fire often need electrical, egress or fire-separation work the local code now requires.
- Contents inventories. Clothing, electronics and furniture affected by soot, priced at replacement cost where the policy allows.
Additional living expense
Fires often displace families for months. Additional living expense or loss of use covers the increase in your living costs, such as temporary rent, while repairs are made. In New York City and on Long Island, comparable short-term housing is expensive, and the duration the insurer allows is often tied to the repair schedule. We document a realistic rebuild timeline so the panel can value ALE fairly.
Fire claims also raise questions about salvage. Items that look intact may carry soot residue or odour that professional cleaning cannot remove, while others clean up well. Electronics exposed to corrosive smoke can fail weeks later. We distinguish between those categories with cleaning test results and vendor opinions so the panel is not forced to choose between an all-or-nothing position on either side. Where your policy includes replacement cost on contents, we also track which items have been replaced so the depreciation holdback can be claimed in time.
Building a contents claim
Contents are often the most time-consuming part of a fire claim. We help organise room-by-room inventories with age, quantity and replacement pricing, then separate items that can be cleaned from those that must be replaced. The holdback calculator shows how depreciation is typically handled.
Multifamily and mixed-use fires
When a fire touches several units or a storefront, more than one policy and more than one claim are usually involved. Our co-op, condo and commercial appraisal service handles building-side losses, and our Brooklyn page discusses rowhouse considerations.
Questions about fire & smoke damage appraisal
Can I appraise smoke damage if the fire was in the neighbour’s house?
Yes, if your own insurer accepts the smoke damage and you disagree on the amount. Your policy responds to damage to your property regardless of where the fire started.
Does appraisal include additional living expense?
It can. If the dispute is about how much temporary housing and extra costs are owed, that amount can generally be appraised.
Do I have to rebuild on the same lot?
Policies differ. Some allow rebuilding elsewhere or paying actual cash value if you do not rebuild, so check your replacement cost conditions.